Why Construction Loans Fail Without Dedicated Broker Management
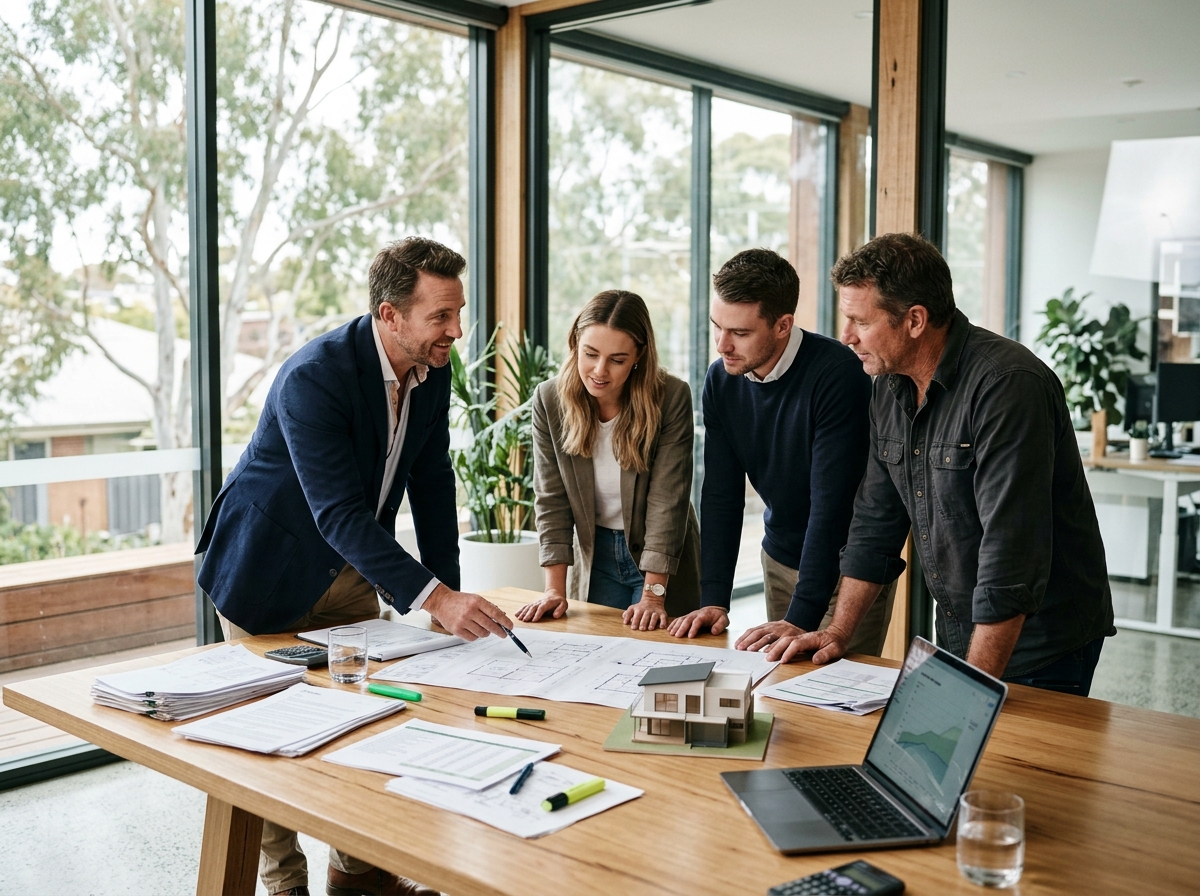
Unlike standard mortgages, construction loans involve multiple parties: you, your builder, private building certifiers, municipal councils, bank quantity surveyors, and lender processing teams. A single missing invoice signature or unapproved variation can delay progress payments for weeks, bringing work on-site to a grinding halt.
Taxnet serves as your dedicated construction project manager on the finance side. We review every progress claim, coordinate bank valuations at critical build stages, and ensure your builder receives funds promptly so your home is finished without costly delays.
End-to-End Financial Support for Every Stage of Your Build
Seamless Transition to Permanent Low-Rate Home Loan
When your builder issues the Certificate of Occupancy, your construction journey reaches its culmination. At this point, final bank inspection occurs, the final retention payment is released, and your construction facility converts into a permanent principal and interest or variable loan.
Taxnet automatically benchmarks your completed property against the market. With your home now physically built and often having achieved substantial equity growth, we renegotiate lower interest rate tiers or add multiple 100% offset accounts to accelerate your mortgage-free timeline.
Start Your Construction Loan Assessment →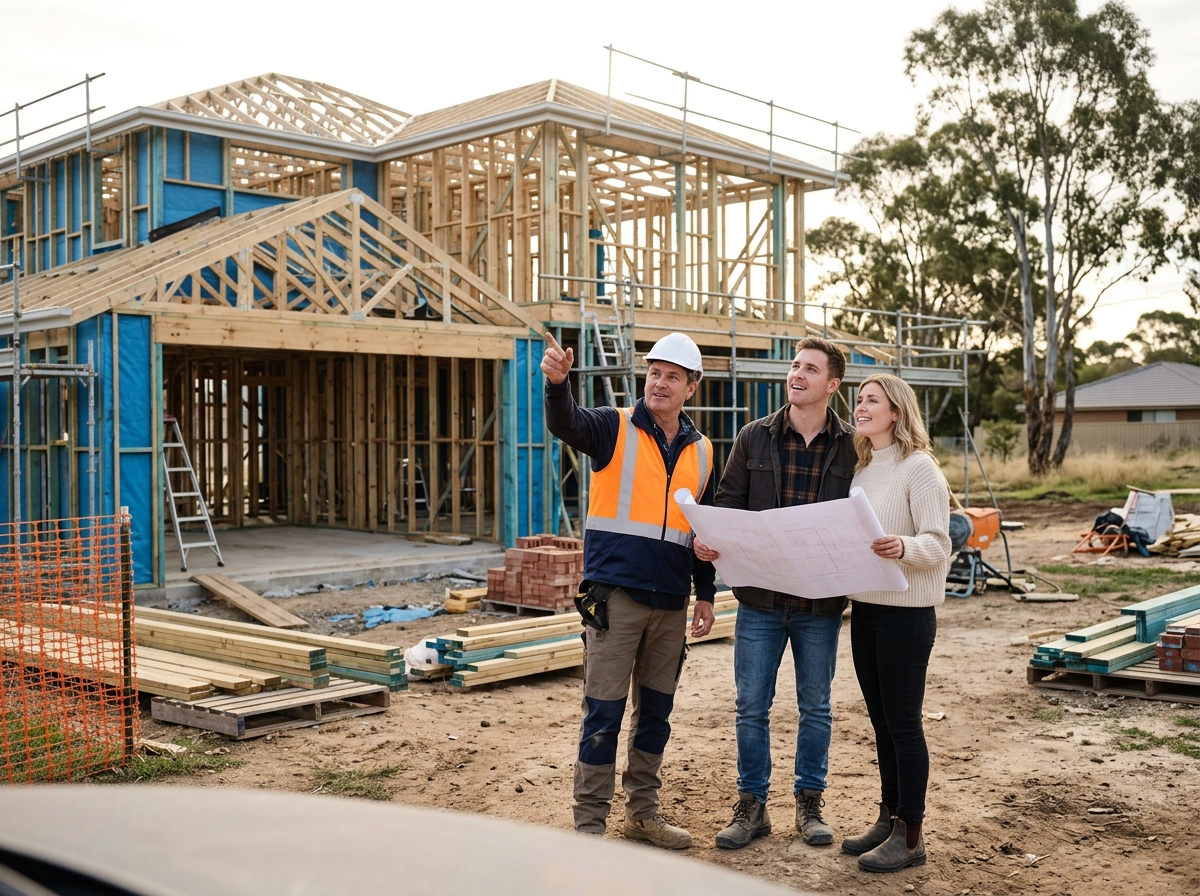
Frequently Asked Questions
How does a progressive drawdown construction loan work in Victoria?+
Unlike a standard home loan where the entire lump sum is transferred on settlement day, a construction loan is released in five progressive tranches as your builder completes each milestone: 1) Base/Slab, 2) Frame, 3) Lock-Up, 4) Fixing, and 5) Practical Completion. The bank inspects the site and pays the builder directly upon receiving a signed progress claim invoice.
Do I pay full principal and interest repayments while my house is being built?+
No. During the construction period (typically 6 to 18 months), your loan operates on an interest-only basis, and you only pay interest on the money drawn so far. For example, if only $100,000 has been paid to the builder on a $500,000 construction facility, you only pay monthly interest on $100,000.
What documents are required to approve a construction loan?+
You will need a signed fixed-price building contract (such as an HIA or Master Builders contract), council-approved architectural building plans and engineering specifications, a detailed schedule of finishes, the builder's current domestic building insurance and registration certificates, and proof of your land ownership or land contract.
Can I use the Victorian First Home Owner Grant ($10,000 FHOG) towards a construction loan?+
Yes. In Victoria, eligible first-home buyers building a brand-new home valued up to $750,000 can receive the $10,000 FHOG. The grant funds are typically released by the State Revenue Office (SRO) at the base/slab stage and applied directly towards the builder's initial progress invoice.
What happens if there are builder variations or unexpected cost increases during the build?+
Builder variations (such as upgrading benchtops or unexpected rock excavation) usually require upfront cash payment or an approved bank loan increase. Taxnet ensures your initial loan includes a prudent contingency buffer so that unexpected site costs never halt your build.
Build Your Dream Home With Confidence
Speak with our Melbourne construction finance specialists to review your building contract, calculate progressive drawdowns, and lock in funding.